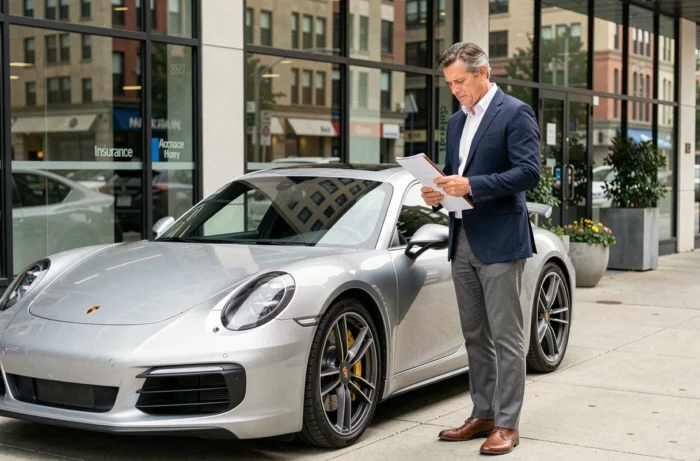
The Porsche 911 is not a vehicle that is insured like a mass-produced sedan. The powertrain, the new or market value, the usage profile (road, leisure, track) and the cost of structural body repairs radically change the contract. Here, we detail the technical points that truly determine the choice of suitable coverage.
Cost of Porsche 911 claims and impact on premiums
Insurers do not price a 911 based solely on its horsepower. The determining factor is the average repair cost per claim, indexed to data from the SRA (Automobile Security and Repair). A Porsche 911 ranks among the most expensive vehicles to restore: specific parts, interventions on aluminum chassis, calibration of driving aids after a collision.
In 2025, the trend observed by France Assureurs confirms that auto claims are less frequent but significantly more costly. The average cost of a theft reaches 4,400 euros, while that of a fire is around 6,731 euros. For material liability, the increase is about 7.5%. These figures, already high for a general fleet, are amplified for a model whose market value and spare parts far exceed the average.
In practical terms, the annual premium for a 911 Turbo with comprehensive coverage will be significantly higher than that of a base Carrera, not due to the difference in raw power, but because the cost of restoring a turbo, an intercooler, or an all-wheel drive system after a claim is of a different order. We recommend always asking the insurer for the SRA grid applied to the exact vehicle type before signing.
To delve deeper into the subject, auto insurance for Porsche 911 deserves a distinct analysis depending on whether the vehicle is recent, a collector’s item, or acquired at auction.
Increased value guarantee and agreed value clause on a 911
For a vehicle whose value can fluctuate significantly (air-cooled 993 models have seen their value double in a few years, while a 996 remains more accessible), the agreed value clause changes everything in the event of a total loss. A standard contract compensates based on the market value at the time of the claim, estimated by the expert. For an older 911 in concours condition, this gap between market value and expert estimate can represent several tens of thousands of euros.
The agreed value contractually fixes the compensation amount, periodically re-evaluated (generally every two or three years). We observe that some “prestige” contracts include this clause as standard, while others offer it as an option with an additional premium. A common pitfall: an agreed value fixed since subscription, never re-evaluated, which no longer reflects the actual value of the model.
Recent or nearly new vehicle
For a new 911 type 992, the new value guarantee (reimbursement of the purchase price for 12 to 24 months) is a more relevant lever than the agreed value. Beyond this period, switching to an agreed value or increased value (compensation above the Argus value) protects against rapid depreciation in the first years.
Older or collector model
For a 911 eligible for a collector’s contract (generally over 25 years old, leisure use), the agreed value is the norm. The technical issue revolves around the frequency of re-evaluation and the required documentation: restoration invoices, contradictory expertise, dated photos. A collector’s contract without periodic re-evaluation is effectively an underinsured contract.
911 insurance and track use: exclusions to be aware of
A 911 GT3 or GT3 RS owner participating in track days faces almost systematic exclusions from standard auto contracts. Most insurers explicitly exclude any use on a track, including non-timed driving days.
- Some specialized brokers’ “prestige” contracts offer a track extension, but with very high deductibles and a reduced compensation ceiling compared to the road contract.
- A dedicated track insurance (taken out for a day or a year) covers material damage to the vehicle, sometimes civil liability on track, but rarely the driver themselves without a specific option.
- The combination of a comprehensive road contract and a separate track insurance remains the most protective configuration, provided there is no cross-exclusion clause between the two contracts.
We recommend carefully reading the contractual definition of “track”: some contracts also exclude regularity rallies or supervised driving courses, which are not competitions.
Driver profile and bonus-malus coefficient on high-performance vehicle
The reduction-increase coefficient (CRM) weighs heavily on the premium of a 911, more so than on a mid-range vehicle. A driver with the maximum bonus (0.50) will benefit from a significant reduction, but a single at-fault claim on a high-value vehicle can shift the premium by several hundred euros from one year to the next.
A young driver can no longer be legally prohibited from driving a powerful vehicle since the Constitutional Council’s decision that struck down this provision of the RIPOST law. However, the young driver surcharge (100% increase in the first year, decreasing over three years) still applies and accumulates with the high pricing of a 911. The budget can then become prohibitive.
Parking also directly influences the premium. A 911 parked in a closed and secure garage benefits from a premium discount compared to parking on public roads, where the risk of targeted theft remains high. The theft of Porsche 911s, especially the most sought-after models (GT3, Turbo S), is subject to specific monitoring by automotive theft networks.
Choosing insurance for a 911 is not just about comparing online quotes. Each generation, each version, and each use calls for distinct guarantees. A careful reading of the specific conditions, verification of the SRA grid, and dialogue with a specialized broker remain the three steps that separate a suitable contract from inadequate coverage.